
Why Historical Expired Options Data Matters#
In options trading, what happens after expiry is just as important as what happens before it.
Most traders focus only on live option chains. While that may work for discretionary trading, it breaks down when you want to systematically design, test, and scale options strategies.
Historical APIs that provide expired options data along with Greeks unlock insights such as:
- How premiums decayed into expiry
- How Greeks evolved in the final days
- How volatility collapsed post-expiry
- How different strikes behaved across market regimes
If your goal is data-driven strategy building, expired options data is not optional — it is foundational.
Backtesting: The Core of Strategy Development#
To truly build an options strategy, backtesting is mandatory.
Backtesting allows you to:
- Validate ideas across multiple years and market conditions
- Measure risk, drawdowns, and expectancy
- Separate edge from randomness
- Test exit logic, roll rules, and sizing
However, meaningful options backtesting requires historical data for contracts that no longer exist.
Without expired options data:
- You cannot analyze behavior into expiry
- You miss how Greeks decay and explode
- You cannot evaluate final settlement outcomes
This is why historical expired options APIs are essential for serious traders.
Why Post-Expiry Greeks Are So Important#
Greeks are dynamic — they change rapidly as expiry approaches.
By studying Greeks on expired contracts, traders gain insight into:
- Theta acceleration in the final days
- Gamma expansion near ATM strikes
- Delta convergence to 0 or 1
- Vega collapse regardless of implied volatility
These insights help answer critical questions:
- Was P&L driven by direction, volatility, or time decay?
- How close to expiry does gamma risk become unacceptable?
- Do weekly expiries behave differently from monthly ones?
These answers only come from post-expiry historical analysis.
Understanding the Greeks (and How Traders Use Them)#
Delta (Δ) – Directional Sensitivity#
Measures how much an option’s price changes for a one-point move in the underlying.
Used to:
- Control directional exposure
- Build delta-neutral strategies like straddles and spreads
Gamma (Γ) – Delta Acceleration#
Measures how quickly delta changes as the underlying moves.
Used to:
- Identify explosive risk zones near expiry
- Manage intraday and expiry-day adjustments
Theta (Θ) – Time Decay#
Measures how much value an option loses each day.
Used to:
- Design premium-selling strategies
- Compare decay profiles across strikes and expiries
Vega (V) – Volatility Sensitivity#
Measures sensitivity to changes in implied volatility.
Used to:
- Trade volatility expansion or contraction
- Avoid selling options when IV is underpriced
Implied Volatility (IV)#
Represents the market’s expectation of future movement.
Used to:
- Compare IV to realized volatility
- Time entries around events and expiries
Studying how these Greeks behaved historically — especially into expiry — enables evidence-based strategy design.
Learn More About Options Strategy Construction#
To see how Greeks come together in real trading strategies, explore the strategy resources on nubra.io.
These cover:
- Multi-leg options strategies
- Risk and payoff structures
- Greek exposure across market conditions
They pair naturally with historical expired options data.
Fetching Expired Option Greeks Using Nubra’s Historical Data API#
Below is an example showing how to fetch historical price data and Greeks for expired option contracts using Nubra’s API.
Instrument Naming Format (Current Year)#
For current-year option contracts, the format is:
UNDERLYING + YEAR + MONTH_NUMBER + DAY + STRIKE + CE/PE
Examples:
- NIFTY2611326000CE
- NIFTY25D2326000CE
This format ensures contracts remain addressable even after expiry.
Example Code: Historical Expired Options Data with Greeks#
from nubra_python_sdk.marketdata.market_data import MarketData
from nubra_python_sdk.start_sdk import InitNubraSdk, NubraEnv
import pandas as pd

pd.set_option('display.max_columns', None)
pd.set_option('display.max_rows', 1000)
pd.set_option('display.max_colwidth', None)
pd.set_option('display.width', 0)

# Initialize Nubra SDK
nubra = InitNubraSdk(NubraEnv.PROD, env_creds=True)
mdInstance = MarketData(nubra)

# Fetch historical data
instruments = ['NIFTY2611326000CE', 'NIFTY25D2326000CE']

response = mdInstance.historical_data({
    "exchange": "NSE",
    "type": "OPT",
    "values": instruments,
    "fields": [
        "open", "high", "low", "close",
        "cumulative_volume",
        "theta", "delta", "gamma", "vega",
        "iv_mid", "cumulative_oi"
    ],
    "startDate": "2025-12-01T11:01:57.000Z",
    "endDate": "2026-01-14T06:13:57.000Z",
    "interval": "1d",
    "intraDay": False,
    "realTime": False
})

def tsp_list_to_series(tsp_list):
    return pd.Series(
        data=[p.value for p in tsp_list],
        index=pd.to_datetime([p.timestamp for p in tsp_list], unit="ns")
    )

dfs = {}

for instrument_dict in response.result[0].values:
    for symbol, stock_chart in instrument_dict.items():
        df = pd.DataFrame({
            "open": tsp_list_to_series(stock_chart.open),
            "high": tsp_list_to_series(stock_chart.high),
            "low": tsp_list_to_series(stock_chart.low),
            "close": tsp_list_to_series(stock_chart.close),
            "volume": tsp_list_to_series(stock_chart.cumulative_volume),
            "theta": tsp_list_to_series(stock_chart.theta),
            "delta": tsp_list_to_series(stock_chart.delta),
            "gamma": tsp_list_to_series(stock_chart.gamma),
            "vega": tsp_list_to_series(stock_chart.vega),
            "iv_mid": tsp_list_to_series(stock_chart.iv_mid),
            "cumulative_oi": tsp_list_to_series(stock_chart.cumulative_oi),
        })
        df.sort_index(inplace=True)
        df["symbol"] = symbol
        dfs[symbol] = df

print(dfs[instruments[0]].head())
print(dfs[instruments[1]].head())
Sample Output: Expired Options Historical Data with Greeks#
The output below shows historical OHLC data along with option Greeks for expired NIFTY call options, enabling post-expiry analysis and backtesting.
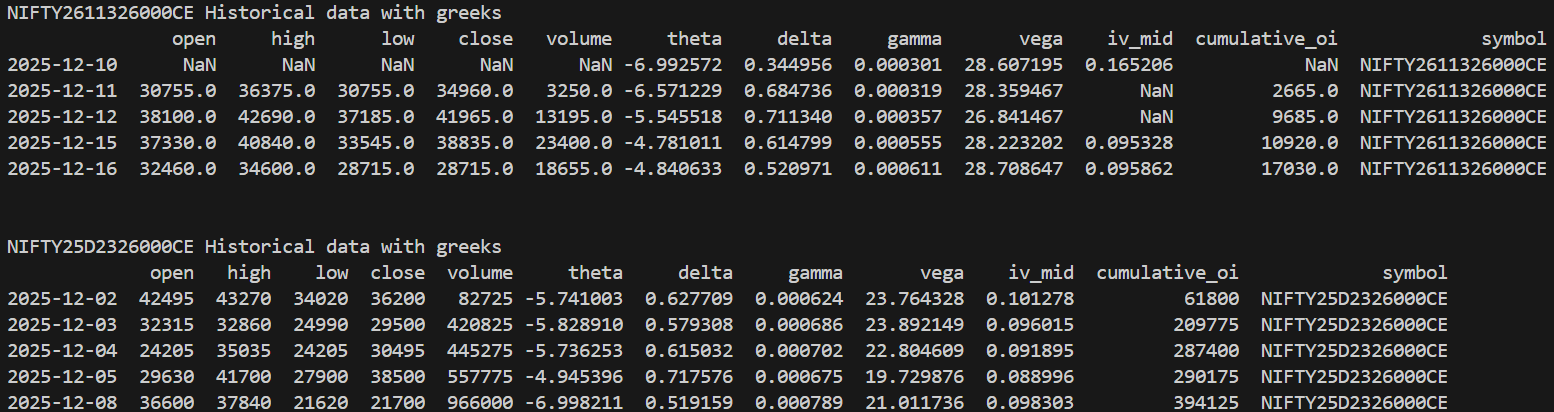
Figure: Historical price data with Delta, Gamma, Theta, Vega, IV, and Open Interest for expired NIFTY options.
Final Takeaway#
Expired options data — especially when combined with historical Greeks — is what separates guess-based trading from evidence-driven strategy design.
With access to expired contracts, you can:
- Analyze Greek behavior into expiry
- Backtest strategies accurately
- Understand volatility and decay dynamics
- Build confidence before deploying capital
If you’re serious about systematic options trading, historical expired options data isn’t a nice-to-have — it’s the foundation.